
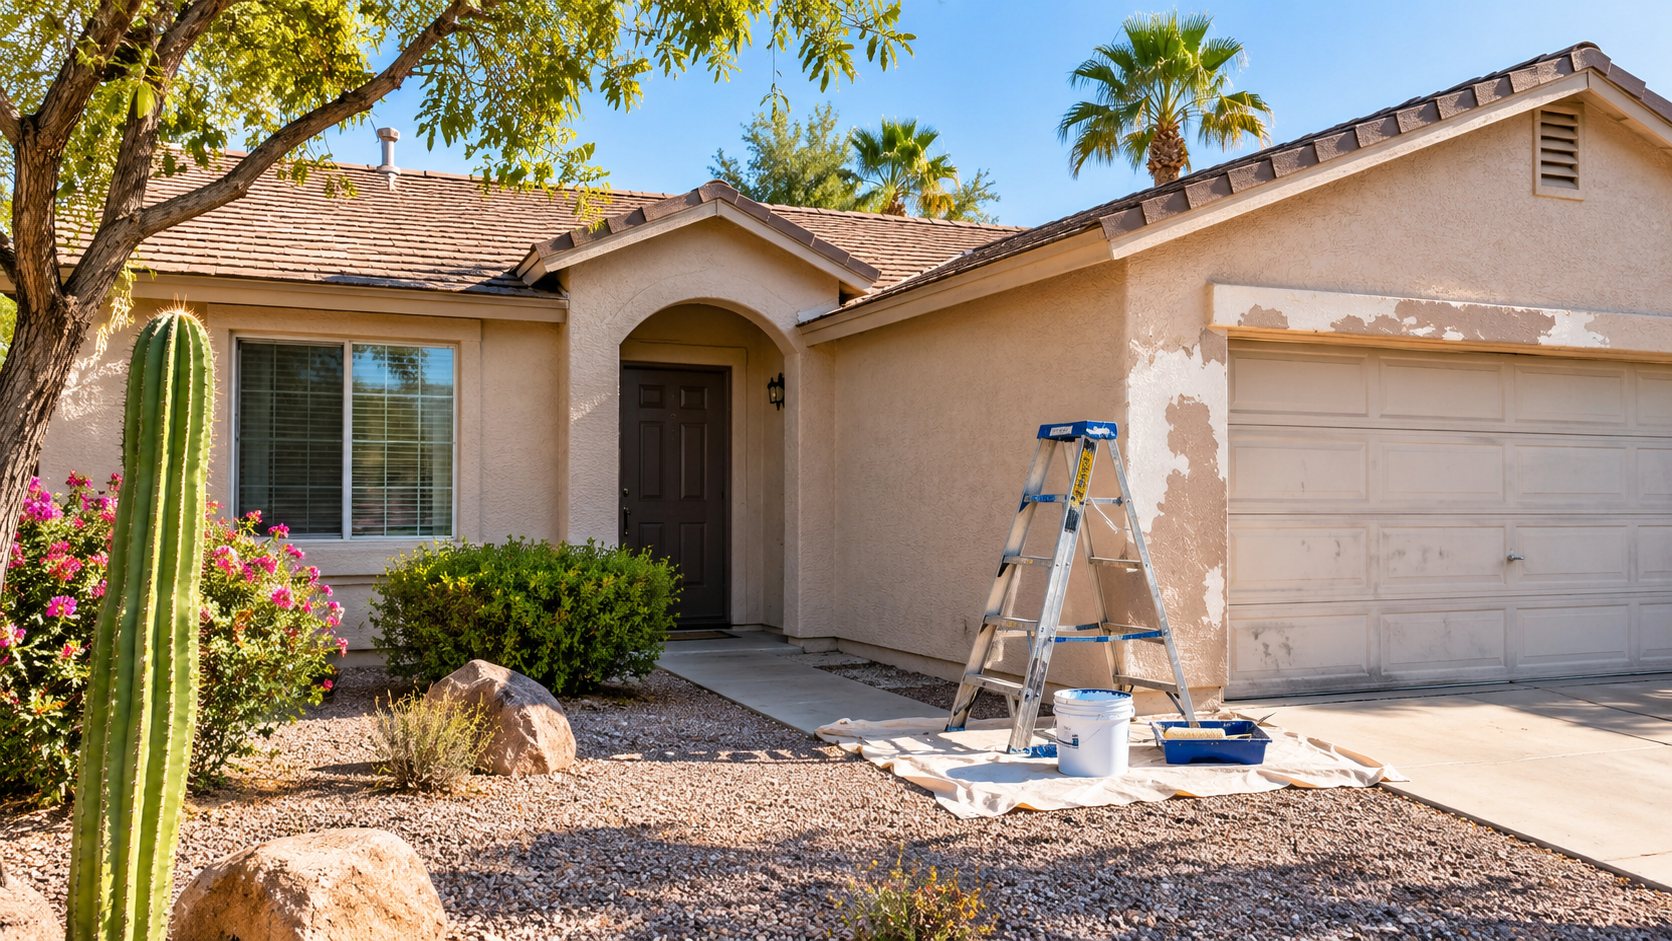
Found a home you love, but worried the repairs will put it out of reach? An FHA 203(k) loan could make that fixer-upper worth a second look.
In this Real Estate Tip Tuesday episode, Katie Halle Lambert with Team EvoAZ at eXp Realty and Ryan Gilliam with Your Best Mortgage discuss how FHA 203(k) loans work and how they could help Arizona home buyers purchase properties that need repairs or updates. They cover the types of renovations that may qualify, the differences between the two loan options, and what buyers should understand before considering this type of financing.
How Does an FHA 203(k) Loan Work?
An FHA 203(k) loan allows buyers to combine the purchase of a home and renovation costs into one mortgage.
For example, if a home costs $350,000 and needs $40,000 in improvements, a qualified buyer may be able to finance both expenses together rather than paying the full renovation cost out of pocket.
Because it's an FHA loan, qualified buyers may also be eligible for a down payment as low as 3.5%.
What Types of Renovations Qualify?
There are two versions of the FHA 203(k) program:
Limited FHA 203(k): Allows up to $75,000 in eligible renovation costs for improvements such as flooring replacement, kitchen and bathroom updates, roof replacement, air conditioning system replacement, and painting.
Standard FHA 203(k): Designed for larger projects, including major structural repairs, extensive remodeling, and additions to the home.
These options may allow buyers to consider properties that need anything from cosmetic updates to more significant repairs.
What Should Buyers Expect From the Process?
An FHA 203(k) loan is more involved than a traditional mortgage because it also finances a renovation project.
Buyers will need contractor estimates, renovation plans, and a lender familiar with the program. Renovation funds are held in an escrow account and released as the work progresses.
The process also requires coordination between the buyer, seller, lender, and contractors. Understanding the planning requirements and renovation timeline upfront is important.
Is an FHA 203(k) Loan Worth Considering?
Some homes may not qualify for traditional FHA financing because of their condition. An FHA 203(k) loan could give buyers a way to purchase those properties while financing the necessary repairs.
If you've found a home that needs work, discussing the program with a lender can help you understand the process and whether it makes sense for everyone involved.
Prefer to Watch Instead?
Found a home you love but worried about the cost of repairs?
Watch the full episode to learn how FHA 203(k) financing works and what to consider before deciding whether it's the right option.
Have Questions About Buying or Selling a Home?
Team EvoAZ can help you navigate the real estate side of your purchase and understand the documents and deadlines that come with an Arizona home transaction.
Katie Halle Lambert | Team EvoAZ
Text ConnectWithKatie to 480-508-9828
Have Questions About Your Mortgage?
Whether you're purchasing your first home, refinancing, or simply have questions about your financing options, Ryan is here to help.
Ryan Gilliam | Your Best Mortgage
Text ConnectWithRyan to 480-508-9828
〰️
Looking for homes in the Phoenix area? Text GetPhoenixDeals to 480-508-9828 to browse current listings and great opportunities.
〰️ Looking for homes in the Phoenix area? Text GetPhoenixDeals to 480-508-9828 to browse current listings and great opportunities.
Disclaimer: The builder incentives and interest rates discussed reflect examples shared at the time of recording and may no longer be available. Incentives, financing terms, and eligibility vary by builder, property, and individual circumstances. This content is for educational purposes only and is not financial or legal advice. Consult a licensed lender, real estate agent, or qualified professional for guidance specific to your situation.
